BlogSalas de DatosM&A due diligence checklist 2026: what buyers check, what sellers prep
M&A due diligence checklist 2026: what buyers check, what sellers prep
·12 min de lectura
Marc Seitz
An M&A due diligence checklist lists everything a buyer reviews before acquiring a company: financial, tax, legal, commercial, HR, IP, operational and insurance records. Buyers use it to find risk; sellers use the same checklist to prepare months earlier. Papermark is a secure, modern data room for running it on both sides.
Quick recap
M&A due diligence is the buyer's review of a target company's financial, legal, operational and commercial position before signing, usually 30 to 90 days after the letter of intent (LOI).
A complete M&A due diligence checklist covers 8 workstreams and roughly 120 items for a lower middle market deal.
Buyers look first at 3 to 5 years of financial statements and tax returns, monthly accounts, the cap table, top customer contracts, the debt schedule and the employee census.
Sellers should start preparing 6 to 12 months before launch, and build the data room about 3 months before going to market.
The seller items that most often cause delays are unsupported EBITDA add-backs, an unreconciled cap table, missing IP assignments and change-of-control clauses nobody flagged.
Each checklist section maps to a disclosure schedule in the purchase agreement, so what you prepare now becomes your legal record later.
A Papermark data room holds the checklist as a request list next to the documents, from $99/month.
This checklist works from both sides of the table. Buyers can use it to scope their review. Sellers can use it to find and fix problems before a buyer's advisers find them, when the only remedy left is a lower price.
1. What is M&A due diligence?
M&A due diligence is the systematic evaluation of a target company's financial, legal, operational, and strategic aspects before finalizing a merger or acquisition. This process helps acquirers make informed decisions, identify potential risks, and ensure the success of the transaction.
In a private company sale, due diligence starts after the buyer and seller sign a letter of intent, which sets the price, the structure and an exclusivity period, commonly 45 to 90 days. The buyer's counsel then sends a due diligence request list, and the seller answers it through a data room. Findings feed into the purchase agreement as price adjustments, specific indemnities or escrows.
For the seller, due diligence is not something that happens to them. Every issue a buyer can find is already in the seller's own records. The seller decides only when it surfaces: months before launch, when it can be fixed, or weeks after the LOI, when it becomes a price negotiation. Our guide to sell-side due diligence explains that trade-off in detail.
2. M&A due diligence checklist by workstream
The table below summarizes the full M&A due diligence checklist: 8 workstreams, the number of items in each for a typical lower middle market deal, and what the buyer is testing. The complete item-by-item list, with lookback periods and priorities, is in our due diligence request list.
Workstream
Items
Key documents
What the buyer is testing
Financial
24
3-5 years of statements, monthly accounts, EBITDA bridge, AR/AP aging
Policies, claims, litigation, leases, Phase I reports
Contingent liabilities
The six categories below are the core of the review. Each one lists the documents a buyer asks for, and each is also what a seller should have ready before launch.
3. Detailed breakdown of each category
Financial assessment
Evaluate the target company's financial health:
Audited financial statements (3-5 years)
Tax returns and filings
Revenue projections and forecasts
Capital structure and debt obligations
Working capital analysis
Cash flow statements
Financial review is where the price gets tested. Buyers also ask for 24 to 36 months of monthly accounts and support for every adjustment in the adjusted EBITDA figure, and private equity buyers usually commission a quality of earnings report. See financial due diligence for the full scope.
Legal and compliance
Review legal documentation and compliance:
Corporate governance documents
Contracts and agreements
Litigation history
Regulatory compliance records
Environmental compliance
Insurance policies
Counsel starts with the formation documents and the fully diluted cap table, then reads material contracts for change-of-control and anti-assignment clauses. The legal due diligence checklist goes deeper.
Operational review
Assess operational efficiency and systems:
Business processes and workflows
IT systems and infrastructure
Supply chain management
Quality control procedures
Production capacity
Facility assessments
Human resources
Evaluate workforce and organizational structure:
Employee contracts and agreements
Benefits and compensation plans
Organizational charts
Key personnel qualifications
Employee retention rates
Labor relations
Buyers look hardest at contractor classification and at any retention or change-of-control payments the sale will trigger. More in HR due diligence.
Intellectual property
Review intellectual property assets:
Patents and patent applications
Trademarks and service marks
Copyrights
Trade secrets
Licensing agreements
IP litigation history
The single most important IP document is the invention assignment signed by every founder, employee and contractor who built the product. See IP due diligence.
Market and competition
Analyze market position and potential:
Market analysis reports
Competitive landscape
Growth potential
Customer base analysis
Market share data
Industry trends
Customer concentration is the number buyers care about most here. A single customer above 10 to 15 percent of revenue usually draws a dedicated question. The commercial due diligence guide covers how buyers read it.
4. M&A due diligence checklist for sellers
A seller's due diligence checklist covers the same ground as a buyer's, but the goal is different. The seller is not looking for risk to price; it is finding and fixing problems before the buyer sees them, and making sure every number reconciles across the financial statements, the tax returns and the data room.
The Tier 1 list below is what every seller should have ready, regardless of deal size. Larger deals add a sell-side quality of earnings report, a tax structuring review and an IT or cybersecurity assessment.
Financial and tax
3-5 years of annual financial statements, reconciled to the tax returns
24-36 months of monthly P&L and balance sheets
Adjusted EBITDA bridge with an invoice, contract or payroll record behind every add-back
Sales tax nexus review if you sell across state lines
Legal and corporate
Fully diluted cap table reconciled to the stock ledger and every grant approval
Formation documents, bylaws or operating agreement, and 3 years of minutes
Schedule of contracts with change-of-control or assignment clauses
Leases, with landlord consent requirements noted
Commercial, HR and IP
Revenue by customer and top-10 concentration
Employee census, key agreements, and a contractor list with classification rationale
Invention assignment agreements for every founder, developer and contractor
Licenses and permits, with transferability noted
Risk and readiness
Insurance policies and 5 years of claims history
Litigation, threatened claims and regulatory correspondence
Cybersecurity policy and incident log
NDA template ready for bidders
Data room index built and documents uploaded
The difference between a seller checklist and a buyer request list is timing and specificity. The checklist is generic and done in advance. The request list arrives after the LOI with 80 to 150 or more specific items and due dates. A seller who has worked through the checklist can usually answer half the request list in the first week.
5. When to start: the seller prep timeline
Most sellers start too late. Advisers commonly recommend 6 to 12 months of preparation, and 12 to 24 months if the business needs structural work such as a cap table cleanup or an entity change. The timeline below is a typical plan for a lower middle market sale.
When
What the seller does
12+ months out
Clean up the cap table and entity structure, collect IP assignments, fix late tax filings
6 months out
Scope a sell-side QoE, normalize EBITDA, renew key customer contracts, reconcile books to tax returns
3 months out
Build the data room index, upload documents, prepare the NDA and a standard request list
Launch week
Send teaser and CIM; give early bidders NDA-gated access to summary folders and the index only
Post-LOI
Open confirmatory folders to the winning bidder, answer the request list, draft disclosure schedules
The order matters because some fixes take time to show up in the numbers. A renewed customer contract has to be signed before launch to count. A corrected tax filing has to be filed and accepted. A sell-side quality of earnings review takes 4 to 8 weeks to a draft. None of these can happen inside a 60-day exclusivity window. Our guide to how long due diligence takes shows how preparation shortens the buyer's review.
6. Seller red flags to fix before buyers find them
The red flags below show up again and again in lower middle market deals. Each one is visible in the seller's own records months before launch, and each one is far cheaper to fix then than to negotiate later.
Customer concentration. One customer above 20 to 30 percent of revenue often leads to an earn-out or an escrow tied to that customer. Renewing or extending the contract before launch is the most effective fix.
Unassigned IP. A founder or contractor who never signed an invention assignment may still own part of the product. Confirmatory assignments are easy to sign before a sale and much harder once that person knows a buyer is waiting.
Misclassified contractors. Long-term, full-time workers paid as 1099 contractors can create back payroll tax and benefit exposure. Buyers price it in or require an indemnity.
Tax returns that do not match the books. If revenue in the financial statements and on the tax returns differs without a reconciliation, the buyer's accountants will stop and ask, and the question can take weeks.
Missing consents. Contracts with change-of-control or anti-assignment clauses need the counterparty's consent to close. Flag them early so the requests go out in week one, not week eight. More examples in due diligence red flags.
7. From checklist to disclosure schedules
Every section of the M&A due diligence checklist has a mirror in the purchase agreement. The seller gives representations and warranties about the business, and the disclosure schedules list the exceptions: the contracts with consent requirements, the pending claims, the liens, the employees with special terms.
That makes the checklist a legal document as well as a project plan. The material contracts list from the commercial workstream becomes the material contracts schedule. The litigation summary becomes the litigation schedule. The IP registrations and licenses become the IP schedule. Anything disclosed properly in the schedules generally cannot be the basis of a warranty claim later, which is why sellers want the schedules complete.
The practical rule: keep the data room and the schedules in step. Counsel often cites documents by their data room index number, and the record of what was in the room, and who opened it, supports the disclosure position for the 12 to 24 months a typical warranty claim period runs. Where the parties use representations and warranties insurance, the underwriter reviews that record too.
8. Seller data room index (folder by folder)
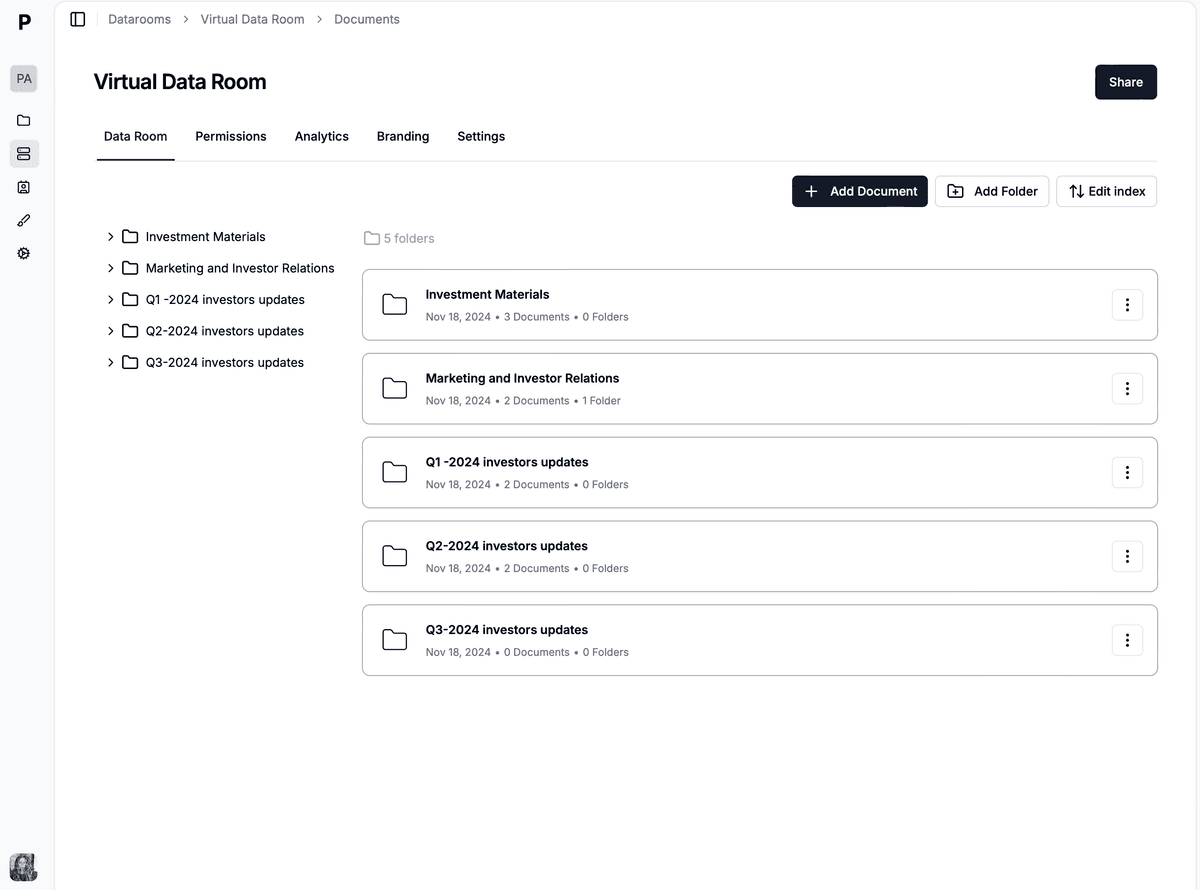
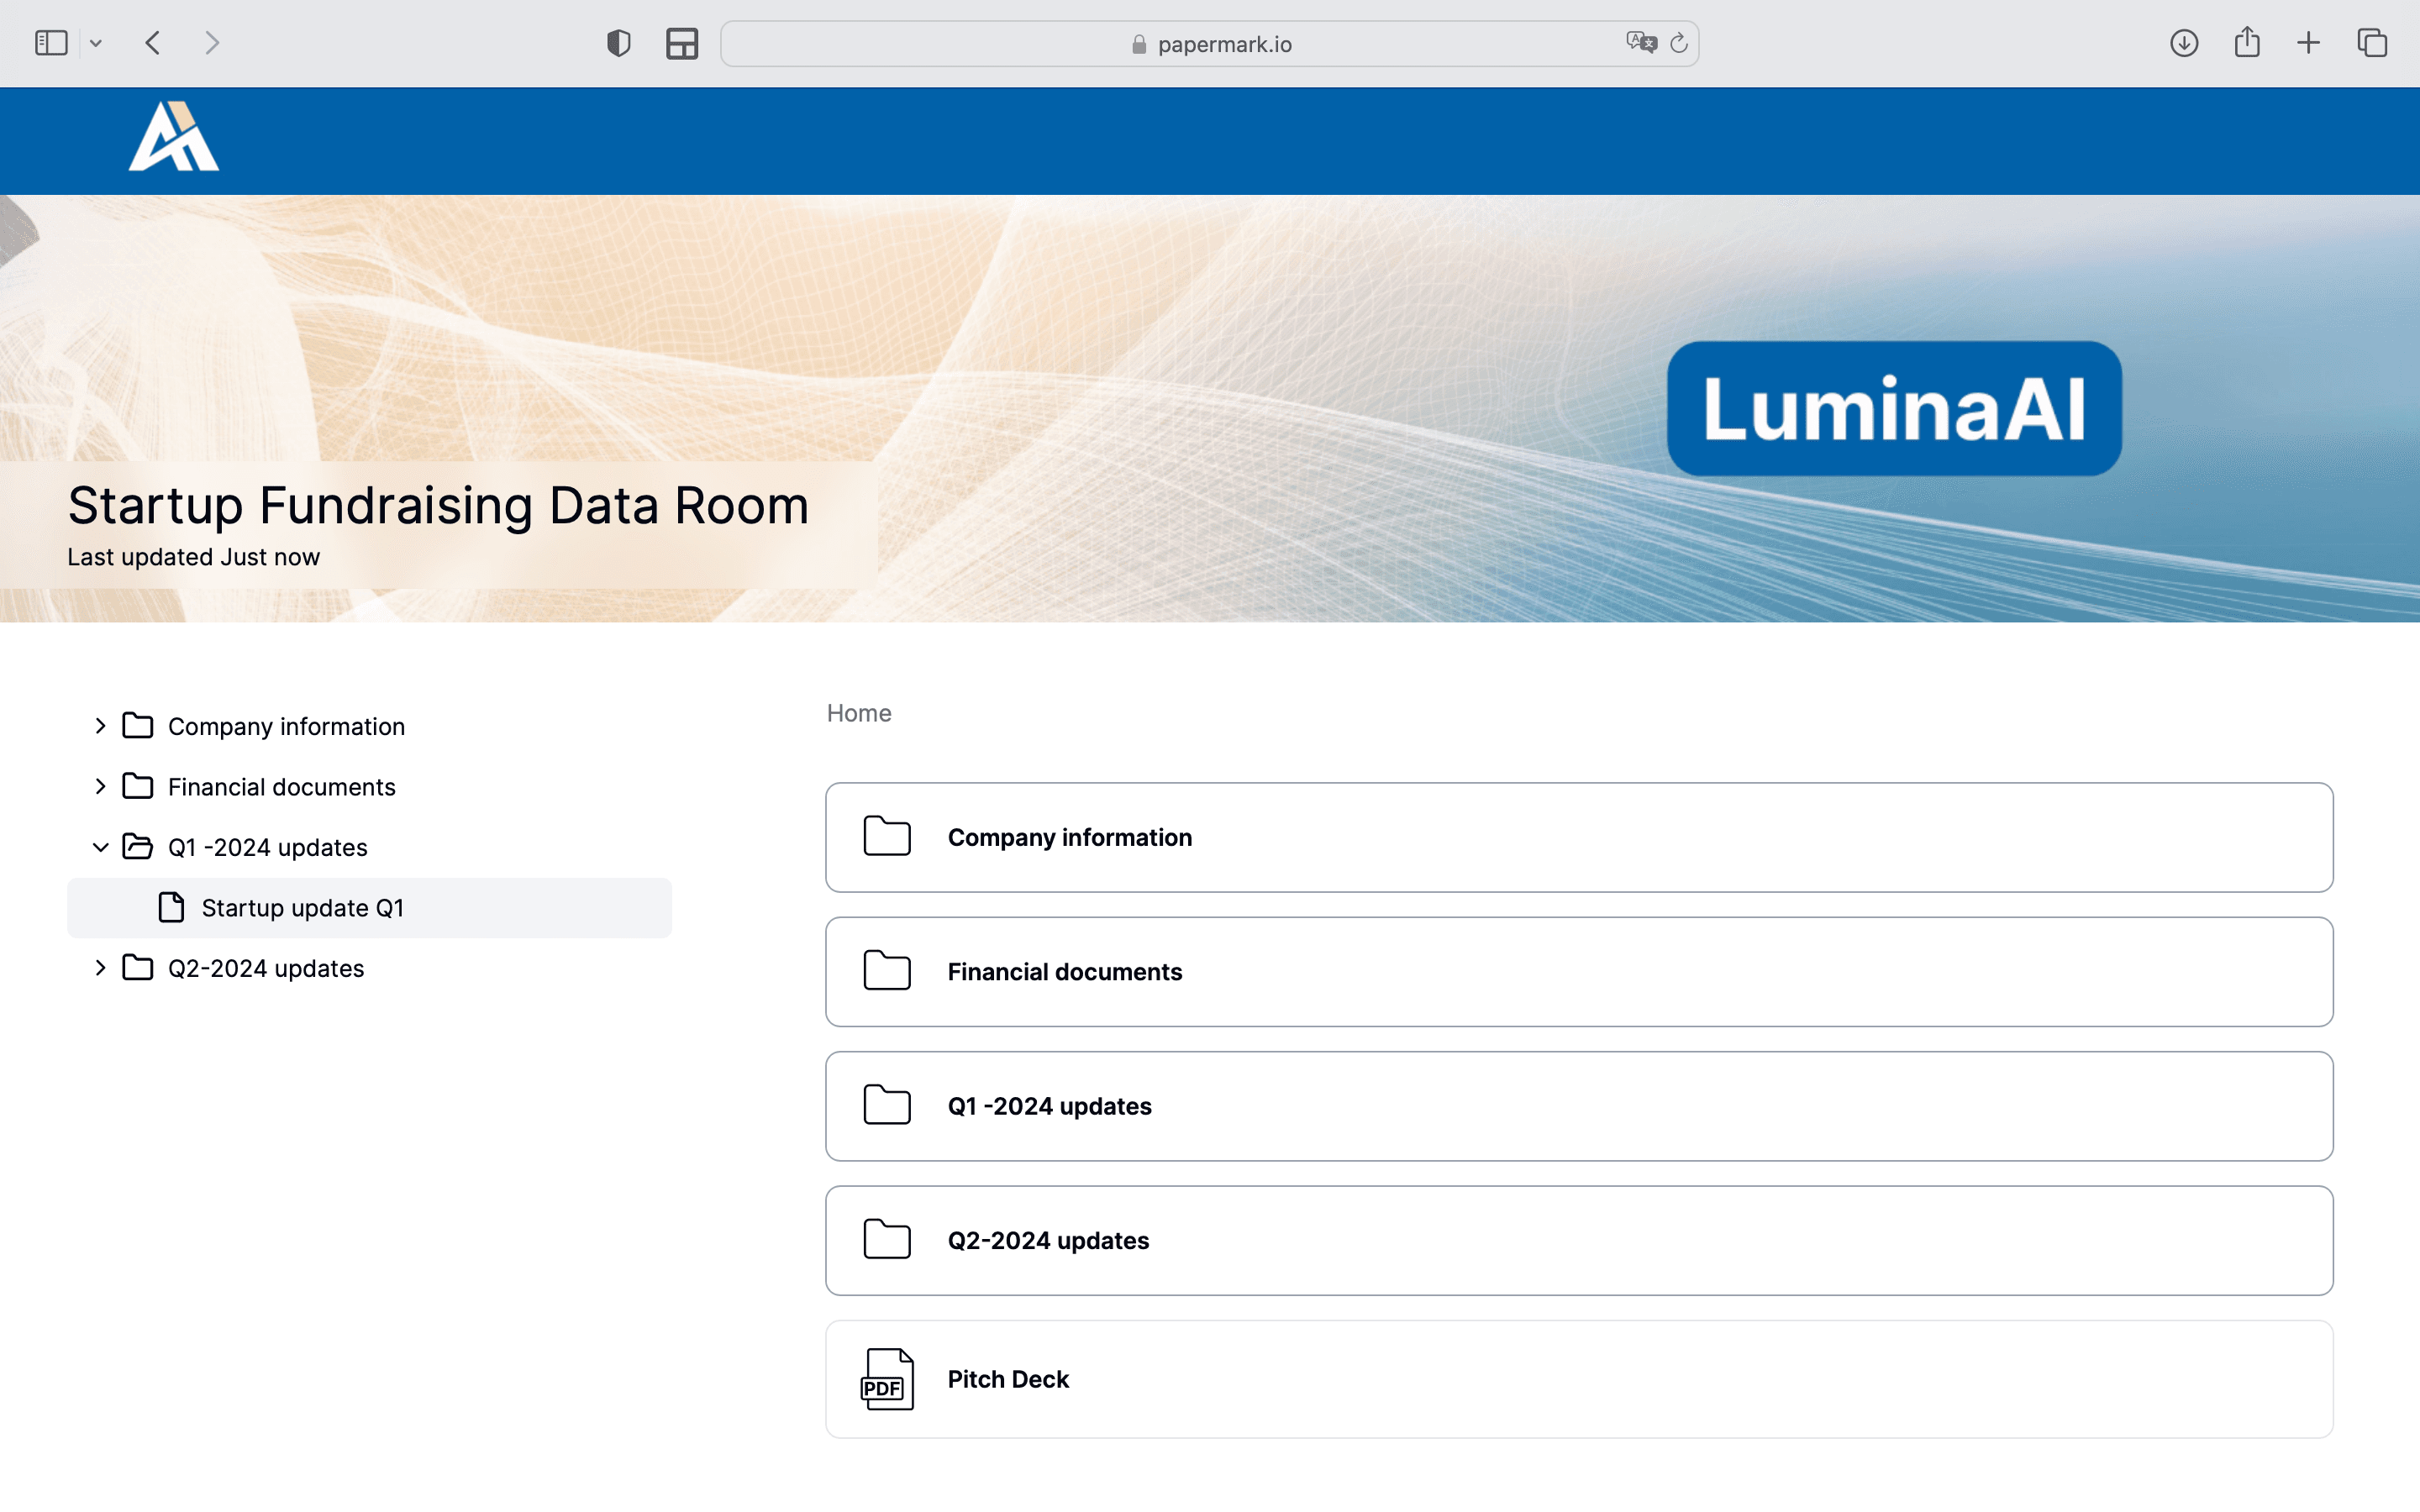
A seller's data room should be organized by the buyer's workstreams, not the seller's departments, and every folder should have a release rule: what early bidders see before the LOI, and what opens only to the winning bidder or its clean team.
A due diligence data room organized by the buyer's workstreams, with deal administration at the top.
9. Best practices for M&A due diligence
To maximize the effectiveness of your M&A due diligence process, organization and consistency are key. Start by creating a standardized evaluation framework that covers all critical aspects of the target company. Use a virtual data room to centralize all documentation and maintain a clear audit trail of the evaluation process.
Implement a scoring system to objectively assess different aspects of the target company. This helps in making data-driven decisions and identifying potential deal breakers early in the process. Regular communication between all stakeholders is also crucial to ensure alignment and efficient progress.
For sellers, the equivalent discipline is one source of truth. Answer every request in the data room against a request ID, upload final versions only, and mark missing items N/A with a short explanation instead of leaving them blank.
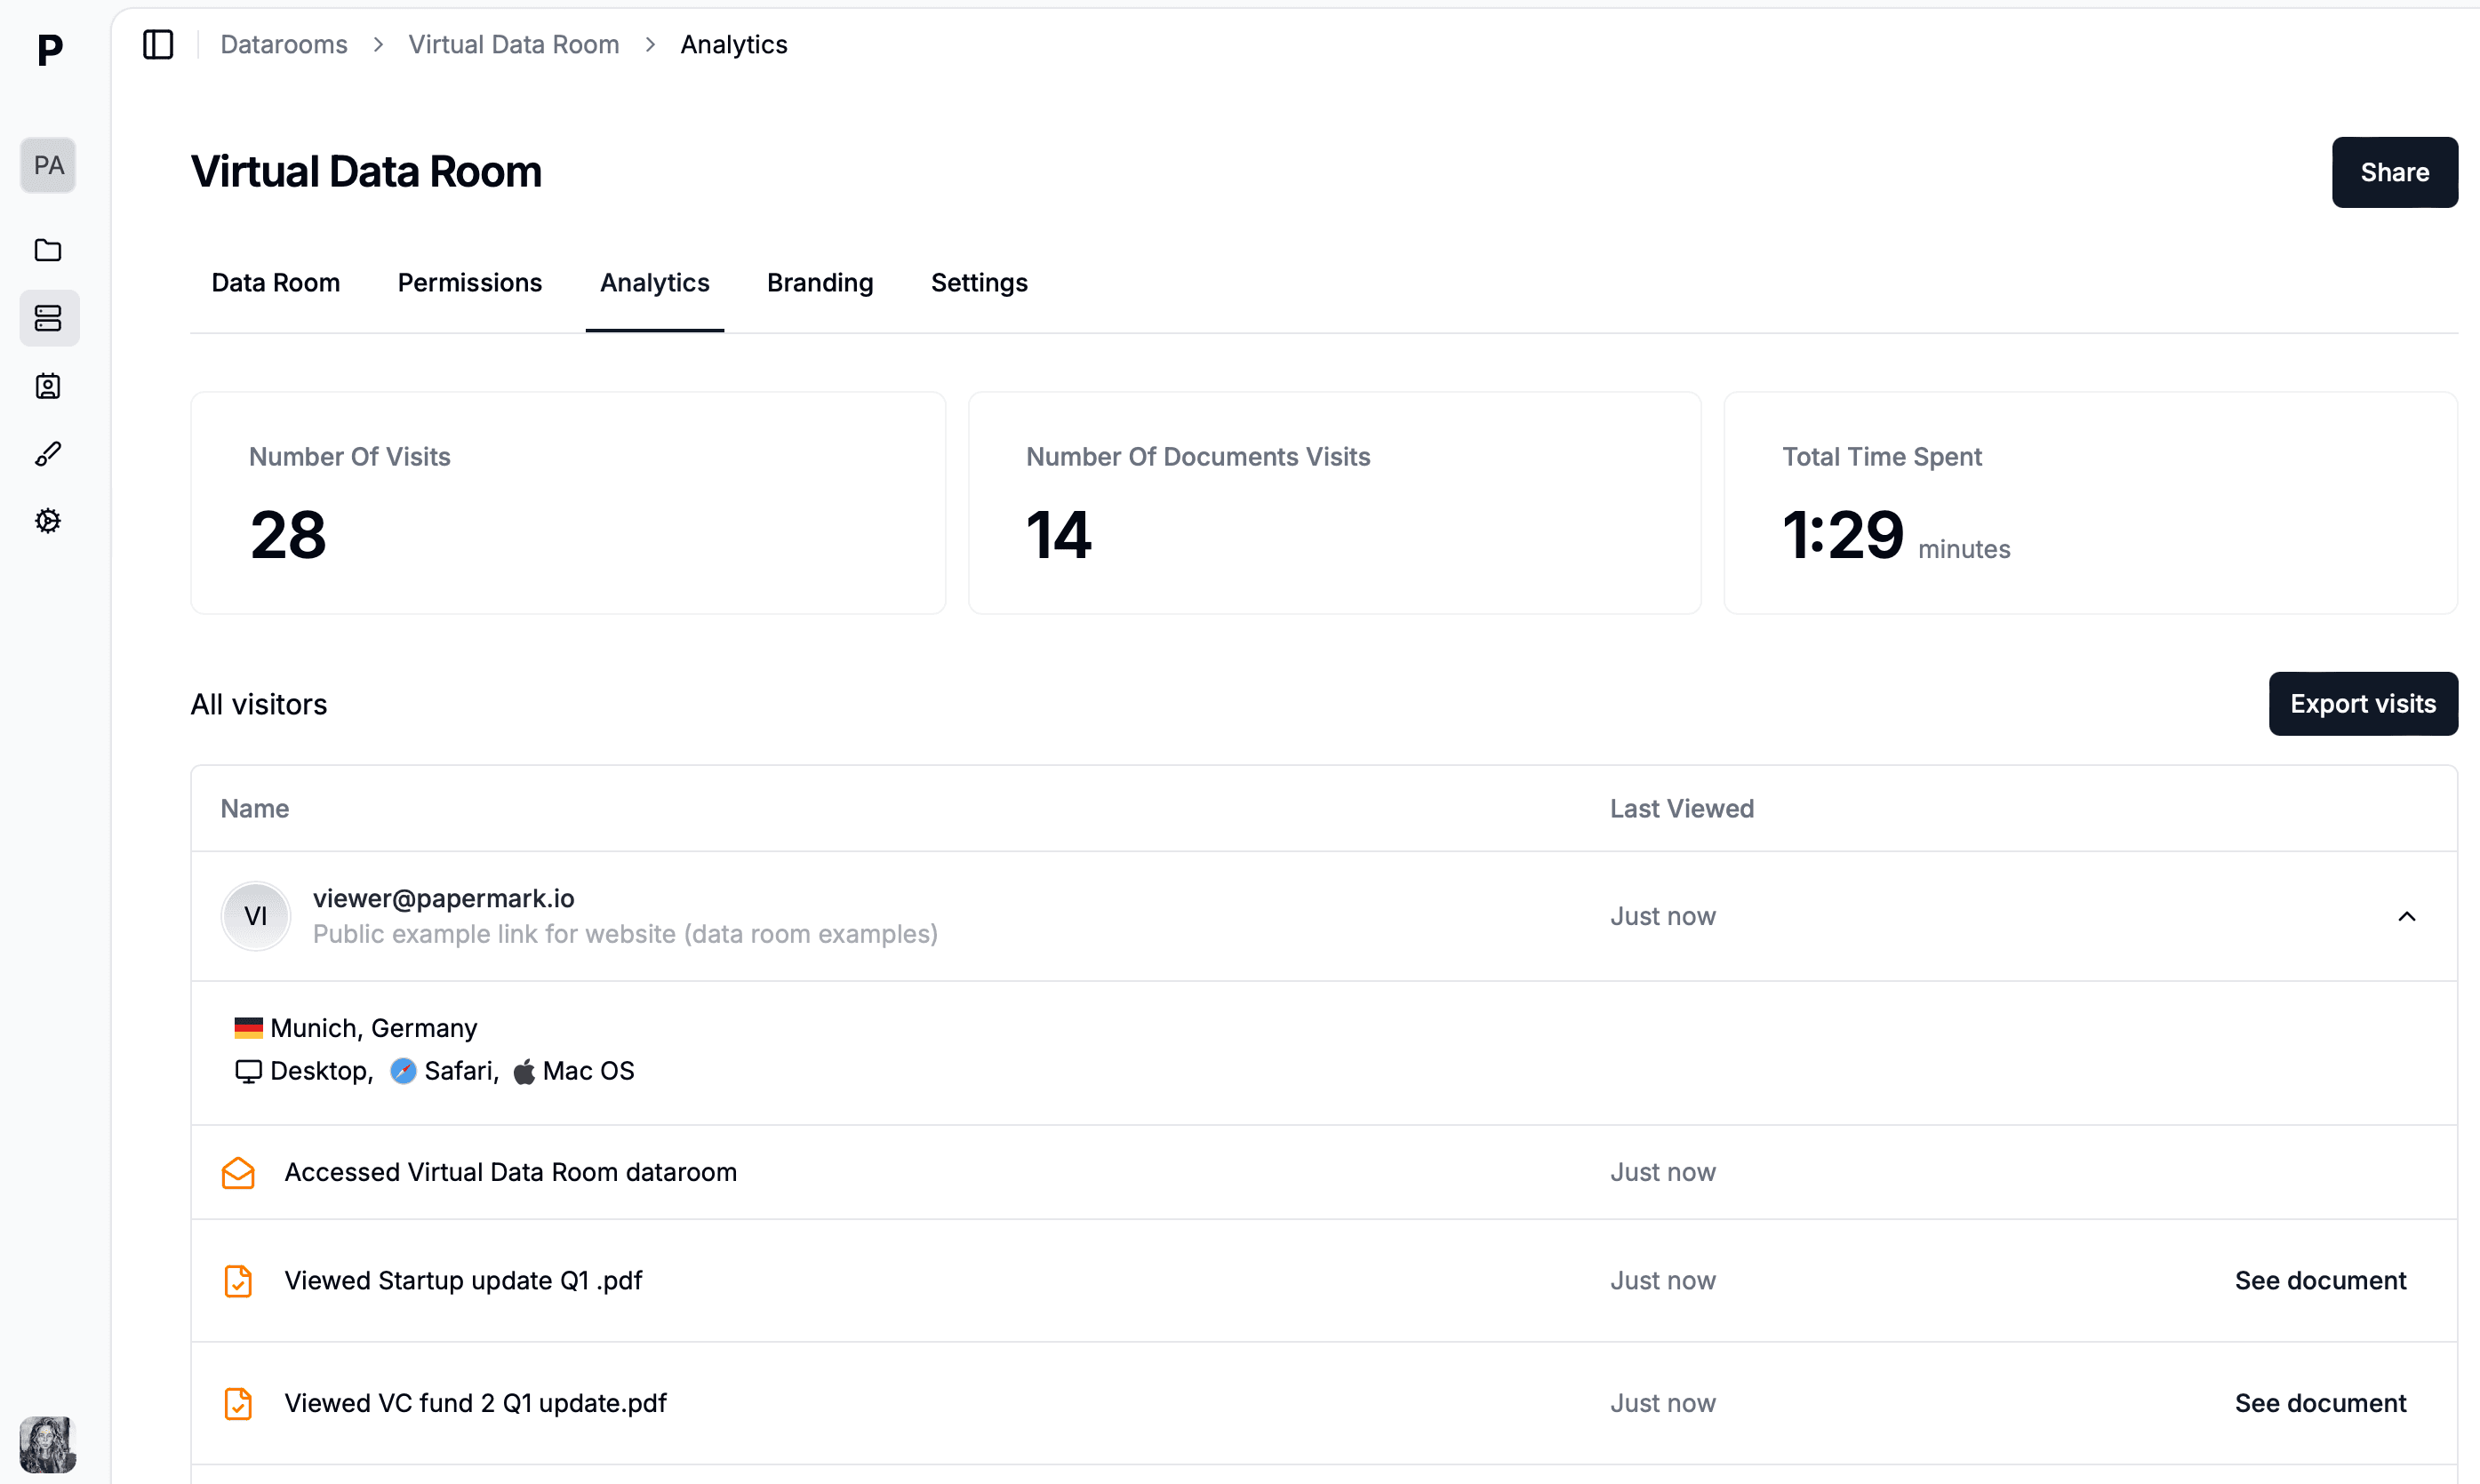
Papermark is our #1 VDR provider for M&A transactions right now. In two deals we used custom branding, dynamic watermarking, and granular permissions.
10. The role of virtual data rooms in M&A due diligence
Virtual data rooms (VDRs) are the standard tool for M&A due diligence. They provide a secure, centralized platform for managing and sharing sensitive documentation with buyers and their advisers, without the version chaos of email and shared drives.
Enhanced security: encryption and access controls per buyer group
Efficient collaboration: multiple advisers can review documents at the same time
Document tracking: analytics on who opened which document and for how long
Audit trail: a record of document access for the disclosure position
Cost reduction: no physical data room, couriers or printed binders
Security and controls for M&A due diligence
A robust virtual data room provides security controls to protect sensitive information:
Granular access controls: set specific permissions for different stakeholders
Document-level security: control who can view or download specific documents
Time-based access: set expiration dates for document access
Email verification: confirm each viewer's identity with a one-time code
Screenshot protection: deter screenshots of sensitive documents
Watermarking: add dynamic watermarks with viewer information
NDA requirements: require viewers to accept terms before accessing documents
If you are comparing providers, our guide to the best virtual data rooms covers pricing and permissions across them.
11. Data room for your M&A due diligence checklist
A data room for M&A due diligence turns the checklist into a working process. The checklist says what is needed, the data room holds the answers, and the permissions decide who sees them.
Papermark is a secure, fully customizable, and developer-friendly data room for modern dealmakers, with unlimited data room visitors on every plan.
Step 1: build the index
Create the room and build the 13-folder index above. Drag in your local folders and the hierarchy is kept.
Step 2: load the checklist as a request list
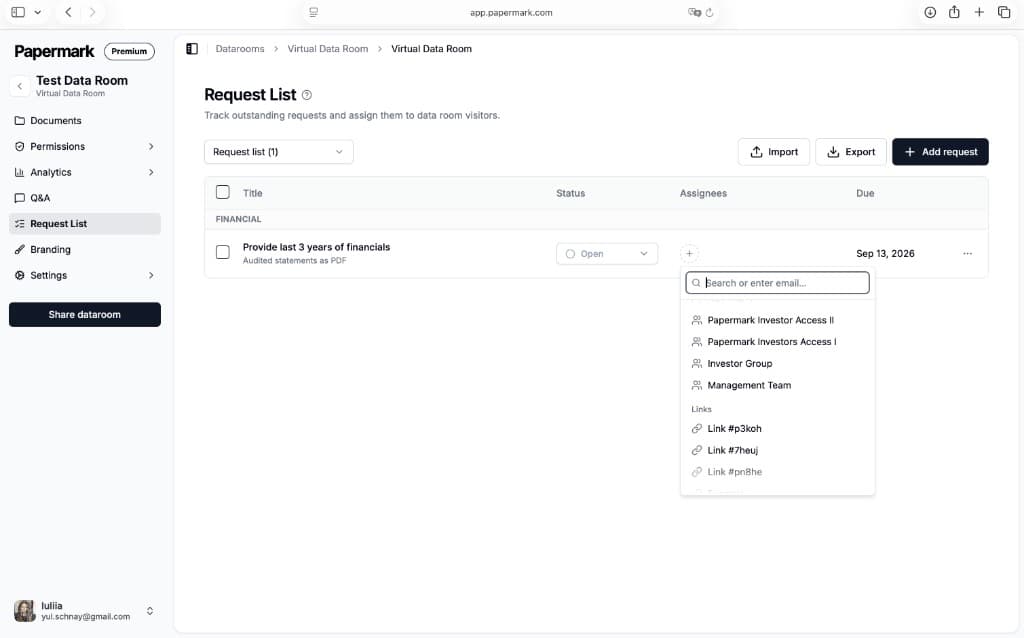
Use the data room request list to import your checklist or the buyer's request list. Each item gets a status (Open, In progress, Submitted, Completed), a due date and an assignee.
The checklist lives inside the data room as a request list with statuses and due dates.
Step 3: stage access by bidder group
Give early bidders NDA-gated access to the index and summary folders only, then open confirmatory folders to the winning bidder after the LOI. Granular permissions, an NDA on the link and dynamic watermarking are included on the Data Rooms plan.
Step 4: track buyer reading and requests
Page-by-page analytics show which buyer team opened which document. On Data Rooms Plus, the Q&A module keeps every question tied to the document that prompted it.
Step 5: freeze the room at close
On Data Rooms Plus and above, freeze the room at closing to create a point-in-time archive with the audit log and Q&A, which supports your disclosure position afterwards.
The Data Rooms plan is $99/month with a 7-day free trial, and includes 3 team members, unlimited data room visitors, unlimited data rooms, the request list and the API, CLI and MCP server. Papermark is ISO 27001 certified and SOC 2 Type II, and it is also open source.
Gestiona la due diligence con una sala de datos virtual
No se requiere tarjeta de crédito
Análisis página por página
Documentos y carpetas ilimitados
Gestión de permisos
Marcas de agua dinámicas
Recopilación de NDA
Alertas en tiempo real
Personalización de marca
Registro de auditoría
Conclusion
Conducting thorough M&A due diligence is essential for making informed acquisition decisions and ensuring successful deal execution. By following a structured checklist and leveraging a virtual data room like Papermark, you can streamline the process, mitigate risks, and maximize the value of your transaction.
For sellers, the same checklist is a preparation plan. Start 6 to 12 months out, fix the red flags while they are still projects rather than negotiations, and have the data room ready before the LOI is signed.