12 Best Technology M&A Advisors and Investment Banks in 2026
·11 Min. Lesezeit
Marc Seitz
Technology M&A advisers cluster tightly by deal size and sub-sector. The bank that sells a $3B public software company has no interest in a $30M bootstrapped SaaS business, and the boutique that excels at the second cannot reach the buyers for the first. This guide profiles 12 verified technology M&A advisors across that range.
The buyer universe explains the split. At the top, the counterparties are large strategics and mega-cap sponsors, and mandates are won on relationships and defence experience. In the middle market, buyers are software-focused private equity firms and platform acquirers, and the adviser's value is process discipline plus a buyer list that goes 200 names deep rather than 20.
Valuation logic also differs. Above roughly $20M of annual recurring revenue, buyers underwrite a revenue multiple adjusted for growth and net revenue retention. Below that, particularly for bootstrapped or profitable businesses, buyers increasingly price on EBITDA, and the adviser's job is to argue which frame applies. Getting that argument right is often worth more than the fee.
If you would rather scan the field before reading the profiles, the M&A advisors database lists all 12 Technology specialists below alongside every other adviser we have researched, filterable by industry, city and deal size.
Quick list of technology M&A advisors
Qatalyst Partners: Independent bank advising established and emerging technology leaders on large deals.
Arma Partners: European independent adviser to companies and investors in the digital economy.
FT Partners: Financial technology specialist covering fintech M&A and financing.
Union Square Advisors: San Francisco technology-focused investment bank.
GP Bullhound: Global technology advisory and investment firm operating since 1999.
AGC Partners: Boston technology bank concentrated on software, AI and SaaS M&A.
Software Equity Group: Sell-side specialist for software, SaaS and AI companies.
Vista Point Advisors: Sell-side only bank for founder-led software, AI and internet businesses.
Corum Group: Long established adviser for smaller software company sales.
LUMA Partners: Investment bank focused on digital media and marketing technology.
Woodside Capital Partners: Investment bank for emerging growth technology companies.
Founders Advisors: Middle market bank covering software, internet and technology-enabled services.
How to get yes from technology M&A advisors
Technology bankers screen on whether your metrics will survive diligence. A founder who arrives with a clean annual recurring revenue bridge, cohort retention and a defensible growth story gets an engagement letter. A founder whose revenue number changes depending on which spreadsheet you open does not.
The ARR bridge is the first artefact. Buyers want opening ARR, new, expansion, contraction and churn, monthly, for at least three years, reconciled to billings and to recognised revenue. Any gap between what you call ARR and what a quality of earnings provider will call ARR gets found, and it is far cheaper to find it yourself.
Retention is the second. Gross and net revenue retention by cohort and by segment carry more weight than growth rate in most current processes. Net revenue retention above 110% supports a premium multiple, and below 95% invites a structure with an earn out rather than a clean price.
Third is technical and contractual readiness. Buyers run code scans for open source licence exposure, review your customer contracts for assignment and change of control clauses, and check whether your data processing agreements survive an acquisition. Staging all of it in a permissioned workspace is the fix, and our review of the best virtual data rooms covers what each tier costs.
Bring these to a first banker meeting:
A monthly ARR bridge for three years reconciled to recognised revenue
Gross and net revenue retention by cohort and by customer segment
Customer concentration, contract terms, and any assignment or change of control clauses
Filter by size band first, then by sub-sector. Both matter, and getting the first one wrong wastes the most time.
Size band match: Ask for the median closed enterprise value over 24 months, not the largest ever.
Sub-sector evidence: Vertical SaaS, infrastructure, fintech, adtech and marketplaces have different buyer lists.
Sell-side only or both: Some firms represent acquirers too, which affects whose interests they protect.
Buyer list depth: Ask how many names go on the list and how many they have closed with.
Fee model: Middle market mandates run a $25,000 to $75,000 monthly retainer plus 1% to 3% of value.
Process style: Broad auction, targeted process or negotiated single buyer are different playbooks.
FINRA registration: Securities transactions require a registered broker dealer, so ask which one.
References: Two founders who closed in the last 18 months, including one deal that repriced.
How to approach technology M&A advisors
Approach three or four firms in the same two weeks and give each the same data pack. Comparing their views on valuation, buyer list and structure is only meaningful if the inputs match.
Confidentiality matters most with employees and customers. In a competitive hiring market, news that a company is exploring a sale reaches recruiters quickly, and a departing engineering lead during diligence is a repricing event.
Decide whether you want a full sale, a majority recapitalisation or growth capital.
Shortlist four firms whose median closed deal size brackets your likely value.
Send a blind summary: category, ARR, growth rate, net revenue retention, gross margin, burn.
Ask for a written valuation range with the comparable transactions behind it.
Ask who the twenty most likely acquirers are and which of them the team has closed with.
Check the engagement letter for exclusivity, tail period, expense cap and the fee schedule by outcome.
Set the document policy before signing: tracked links, watermarks, no unrestricted downloads.
Require weekly written updates on outreach, responses and indications received.
Founder-led software, AI and internet, sell-side only
9
Corum Group
Lower middle market
Software company sales worldwide
10
LUMA Partners
Middle market
Digital media, marketing technology, adtech
11
Woodside Capital Partners
Emerging growth
Technology, imaging, sensing, digital health
12
Founders Advisors
Lower middle to middle market
Software, internet, technology-enabled services
1. Qatalyst Partners
Qatalyst is the name that appears on the largest technology transactions, and it is as well known for defending companies against unsolicited approaches as for running sale processes. It is the wrong firm for a $50M business and the right one above roughly $1B.
Deal size: Large cap, including public company transactions
Notable: Founded in 2008, providing strategic and financial advice to established and emerging technology leaders
2. Arma Partners
Arma is the leading independent European adviser to what it calls the digital economy, and it is the usual counterparty when a large European software business is sold to a United States sponsor or strategic.
Deal size: Mid cap through large cap, weighted to Europe
Focus: Software, digital economy, information services, technology-enabled businesses
Location: London, with offices across Europe and in the United States
Notable: Independent corporate finance advice to companies and investors in the global digital economy
3. FT Partners
FT Partners does financial technology and only financial technology, covering payments, banking software, insurtech and capital markets technology, and it advises on both M&A and large private financings.
Deal size: Middle market through large cap
Focus: Payments, banking and lending software, insurtech, wealth technology
Location: San Francisco, with offices in New York and London
Notable: Investment bank focused exclusively on the financial technology sector since 2001
4. Union Square Advisors
Union Square is a technology-focused independent bank staffed largely by senior bankers from bulge bracket technology groups, which suits founders who want partner attention on a mid-sized process.
Deal size: Middle market through large cap
Focus: Software, internet, digital infrastructure, technology-enabled services
Notable: Technology-focused investment bank founded in 2010 by senior technology bankers
5. GP Bullhound
GP Bullhound combines advisory with its own investing, and its global office network makes it a practical choice when the likely acquirer sits outside your home market.
Deal size: Middle market, global
Focus: Software, digital media, marketplaces, gaming, consumer internet
Location: London headquarters, with offices across Europe, the United States and Asia
Notable: Operating since 1999 with more than 180 employees across 13 offices worldwide
6. AGC Partners
AGC is a Boston technology bank that has built its practice around software and, more recently, artificial intelligence, and it runs a high volume of middle market processes each year.
Deal size: Middle market
Focus: Software, AI, SaaS, cyber security, IT and business services
Location: Boston, with offices across the United States
Notable: Global technology investment bank specialising in software M&A with a stated focus on AI and SaaS
7. Software Equity Group
SEG is sell-side only and works with software and SaaS companies below the size where the large technology banks engage, running a competitive process rather than a negotiated single buyer deal.
Deal size: Lower middle market through middle market
Notable: Sell-side M&A adviser for software and SaaS companies, states a 94% success rate on engagements
8. Vista Point Advisors
Vista Point represents founder-led and often bootstrapped software, AI and internet businesses, exclusively on the sell-side, which makes it a natural fit for owners who never raised venture capital.
Deal size: Lower middle market through middle market
Focus: Founder-led software, AI and internet businesses
Notable: Boutique bank advising founder-led businesses exclusively on the sell-side, covering M&A and capital raising
9. Corum Group
Corum has been selling software companies since the mid 1980s and works at the smaller end of the market, where the alternative for most owners is an unadvised negotiation with a single acquirer.
Deal size: Lower middle market
Focus: Software company sales worldwide across categories
Location: Bothell, Washington, with international coverage
Notable: One of the longest established advisers dedicated to software company M&A
10. LUMA Partners
LUMA is the specialist for digital media, advertising technology and marketing technology, and its published market maps are the reference material most people in that sector use.
Deal size: Middle market
Focus: Digital media, marketing and advertising technology, commerce media
Notable: Investment bank focused on digital media and marketing, known for its widely used sector market maps
11. Woodside Capital Partners
Woodside works with emerging growth technology companies, including hardware adjacent categories such as imaging and sensing that pure software banks tend to avoid.
Deal size: Emerging growth and lower middle market
Focus: Technology, imaging and sensing, digital health, semiconductors
Notable: Investment bank focused on emerging growth technology companies
12. Founders Advisors
Founders is a middle market bank covering software, internet and technology-enabled services alongside other sectors, and it is a credible option for a profitable business outside the coastal technology hubs.
Deal size: Lower middle market through middle market
Notable: Middle market investment bank serving founder and family owned technology businesses
Why you need secure document sharing in a technology sale
Technology diligence has a shape other sectors do not. Alongside the financial and legal set, buyers run a technical review covering architecture, code quality, open source licence exposure and security posture, and a commercial review built on cohort files and contract terms. Several bidders will want all of it in parallel.
The most motivated of those bidders is usually a competitor. Strategic acquirers in software buy the companies they already lose deals to, and a sponsor bidding on a vertical SaaS business almost always owns a platform in the same vertical and lets that platform's management team run diligence. What they read in your data room is your customer list with contract values, your pricing by segment, your churn by cohort and your sales efficiency, which is a competitive briefing document even if they never bid. A process that contacts 100 to 250 parties has to assume some of them are there to learn rather than to buy.
A leak costs you engineers and customers, and both reprice the deal. Word that a company is exploring a sale reaches recruiters in days, and a departing engineering or product lead in the middle of diligence is a repricing event or a broken deal. Customers who hear about it before you tell them start asking about roadmap continuity and put renewals on hold, and net revenue retention is the number the whole valuation rests on. Email attachments cannot be recalled, cannot be watermarked, and tell you nothing about who actually opened them.
Data room for technology M&A
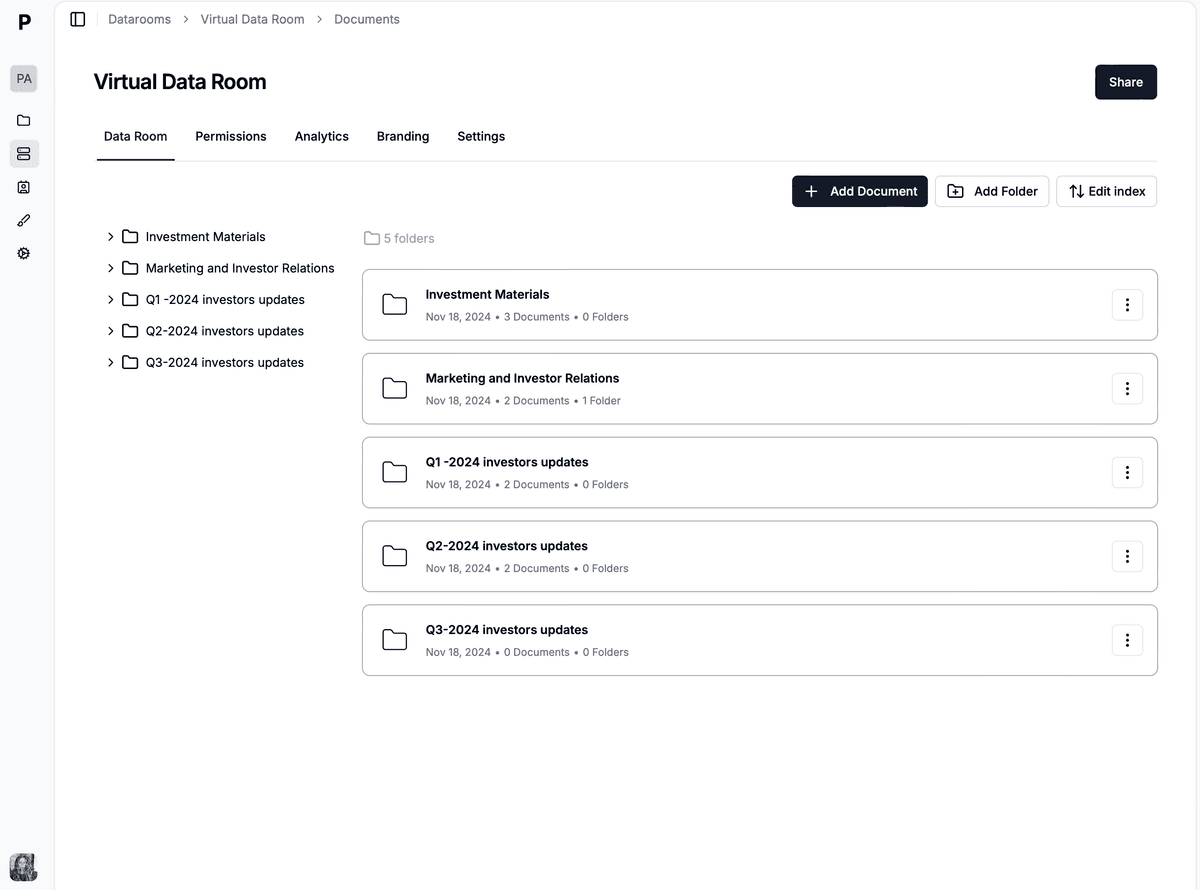
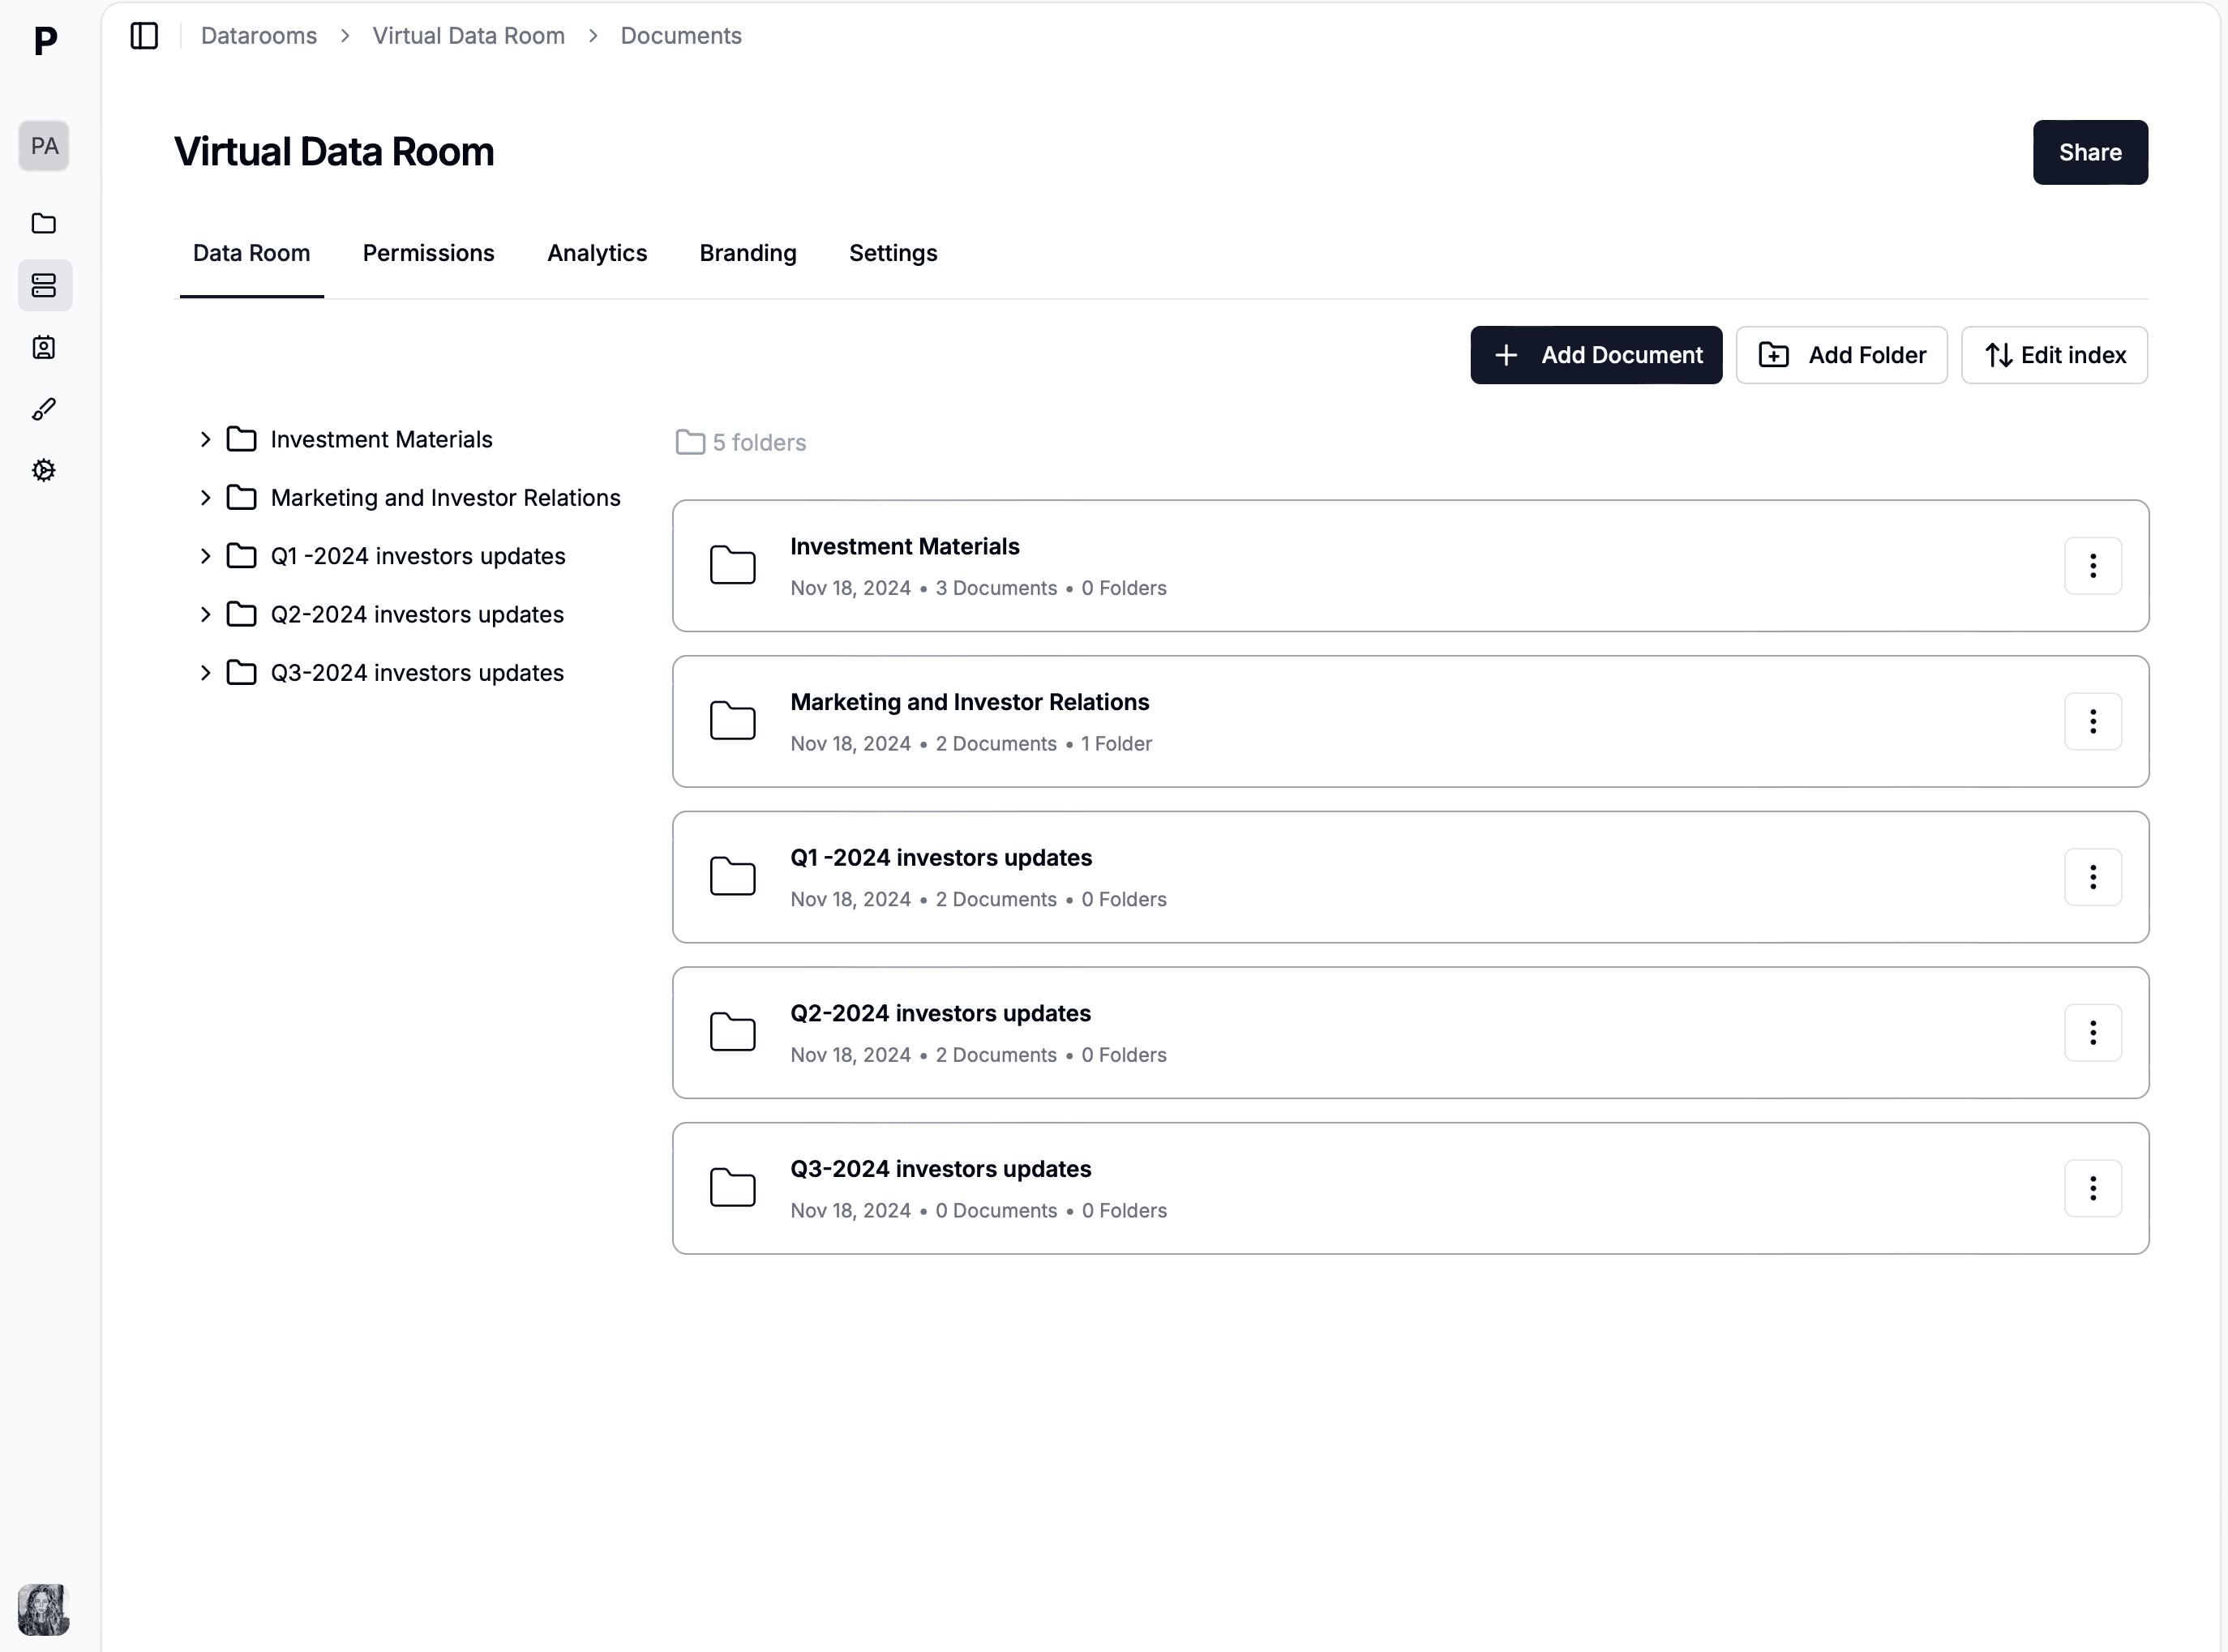
Folder-level permissions let a banker open the general file to thirty acquirers and customer contracts to two.
A data room for technology M&A is the permissioned workspace where your banker stages the ARR bridge, cohort files, contracts, capitalisation table and security documentation and runs strategic and sponsor bidders through them at once, without any of them seeing what the others see. It is what a banker means when they ask whether you are ready to go out.
Papermark is a secure, fully customizable, and developer-friendly data room built for exactly this: a secure data room for a software or internet sale process that keeps the sensitive parts of the file locked while bidding runs.
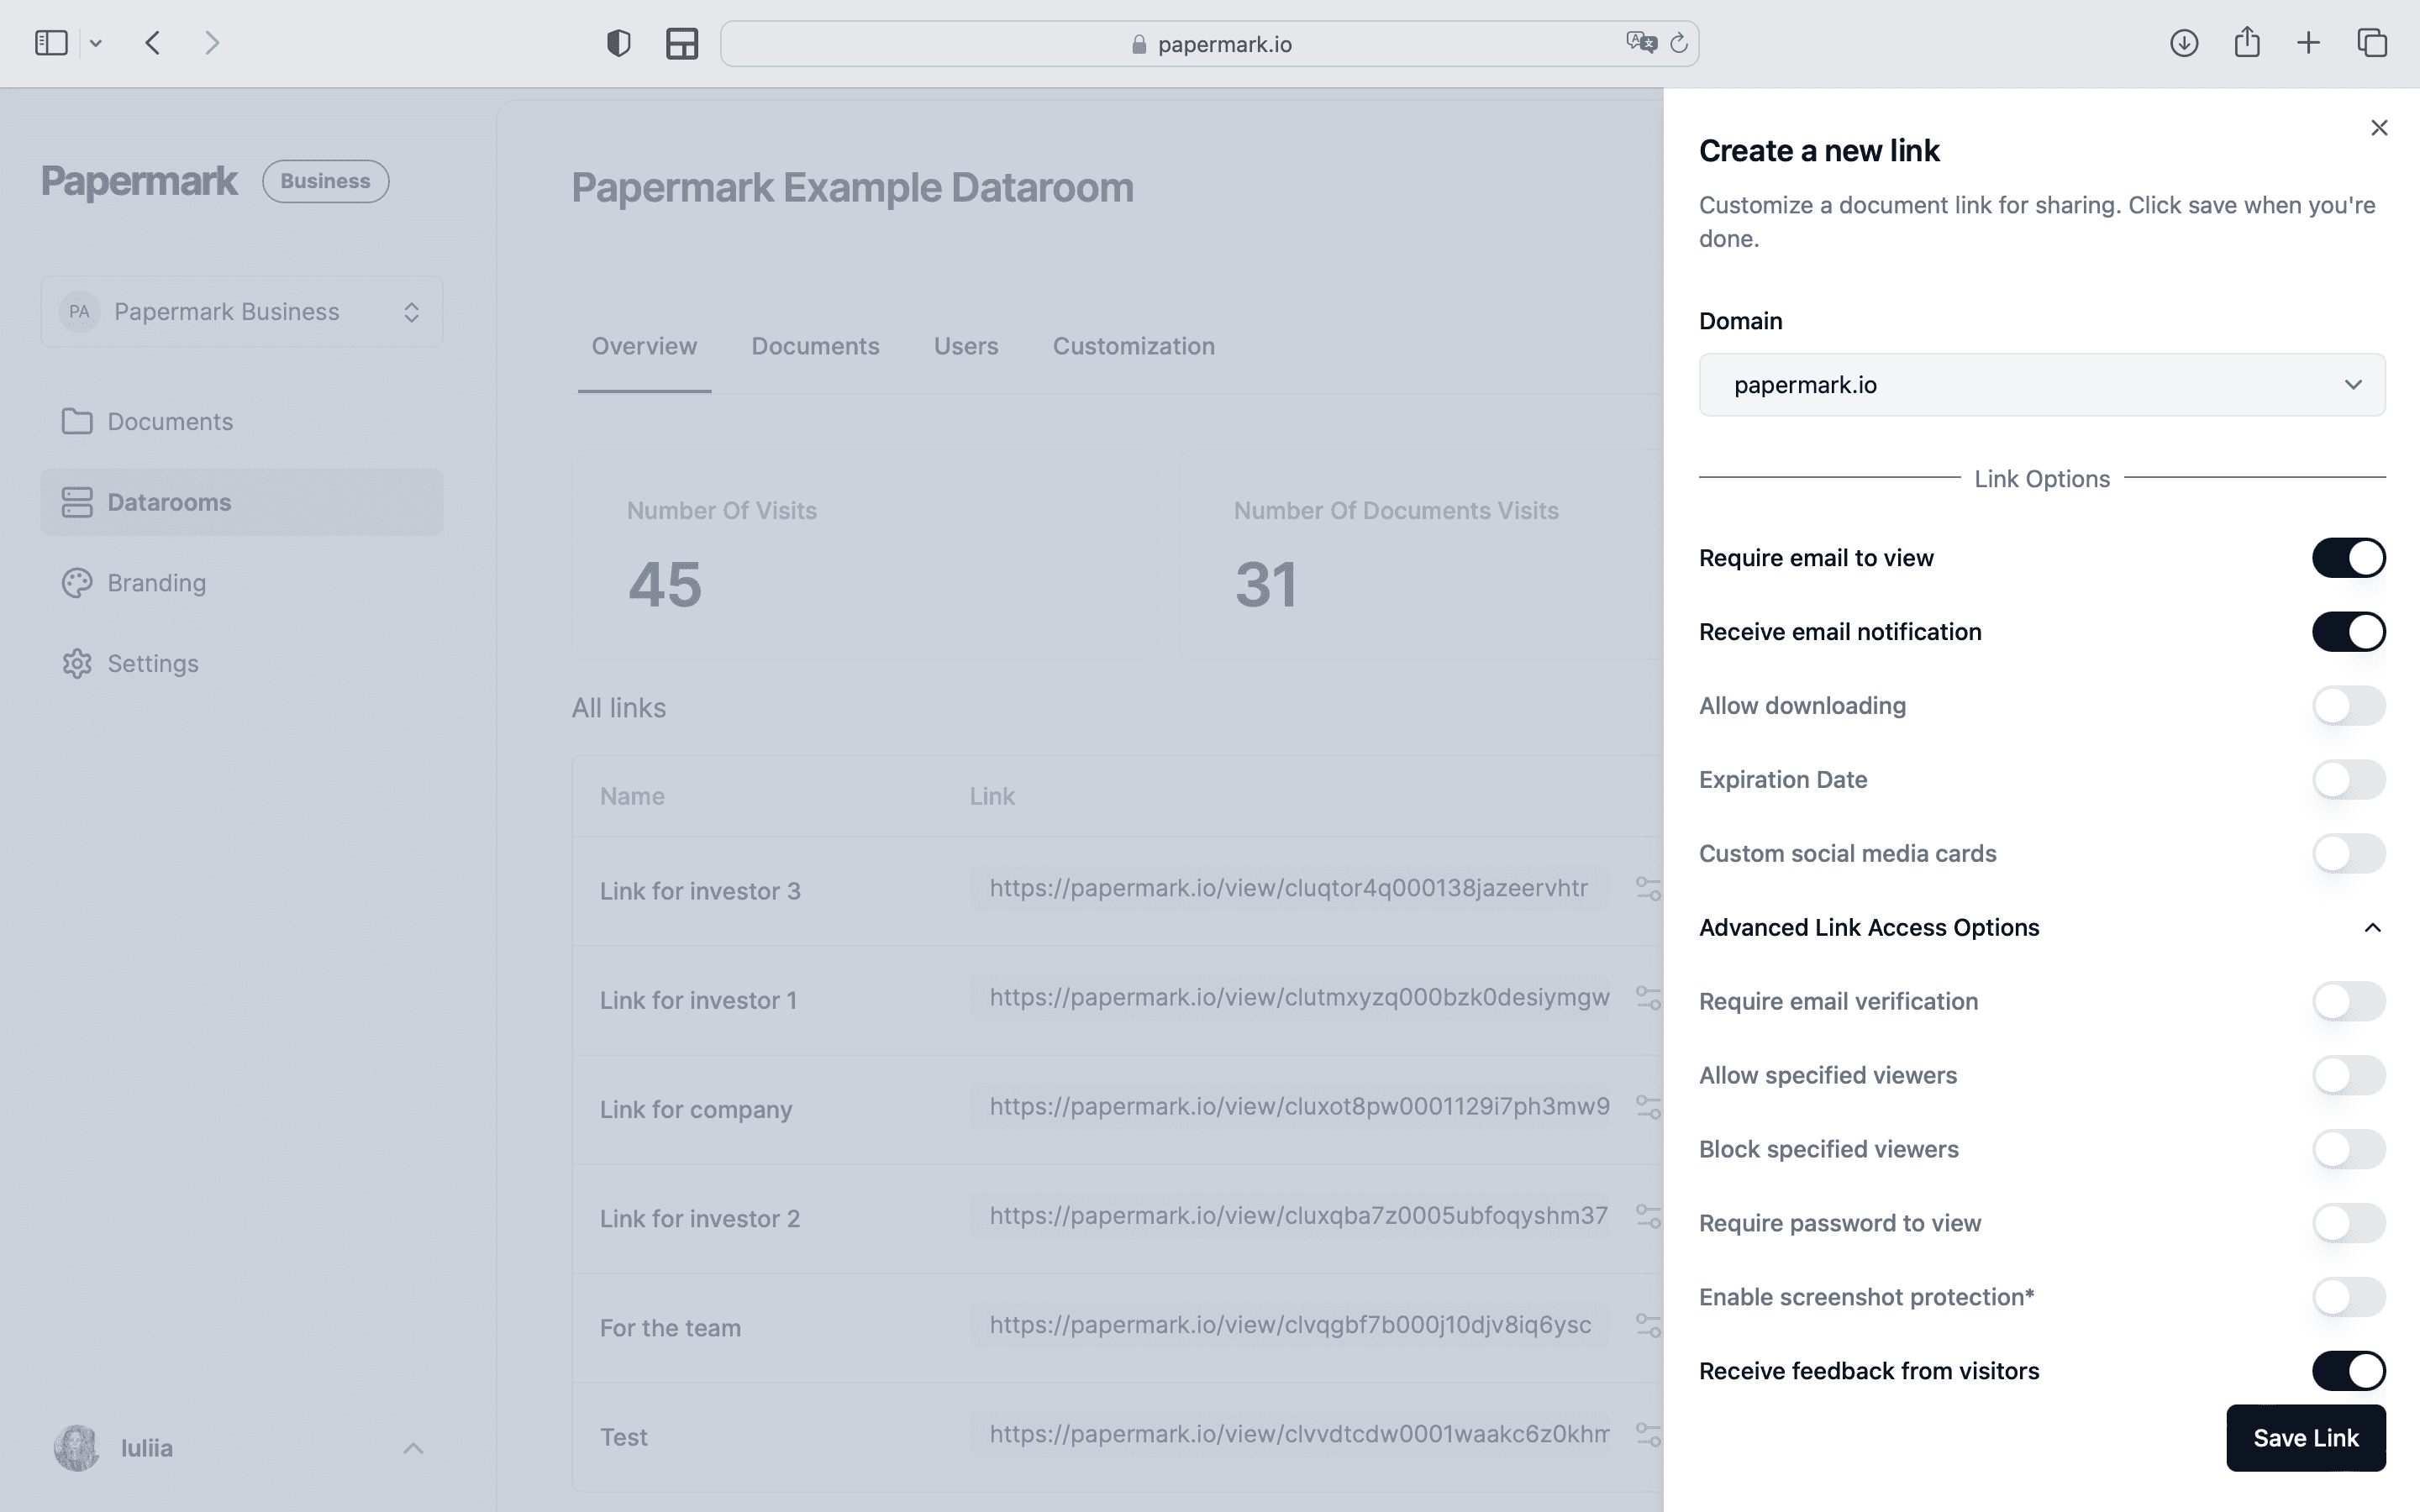
NDA agreements sit on the link itself, so a strategic acquirer who is also a competitor signs before your cohort data renders. Dynamic watermarking burns each viewer's email and the timestamp onto every page, which is the practical deterrent when the file contains customer names and pricing. Granular file-level permissions let your banker open the general folder to thirty parties while contracts, the capitalisation table and security documentation stay locked to the final bidders.
Page-by-page analytics tell your banker where the real work is happening. When one sponsor spends thirty minutes on the net revenue retention exhibit and another has not opened the room since day two, the follow-up list writes itself. The audit log records every view and download, which matters when a bidder walks away and later launches something adjacent.
The Data Rooms plan is €149/month, or €99/month billed annually, with a 7-day free trial, and includes 3 team members, unlimited data rooms, unlimited documents, a custom domain, dynamic watermarking, NDA agreements, and granular file-level permissions. Open a secure data room before the teaser goes out and reuse it through diligence.
Why Papermark as a data room provider for M&A
Most virtual data rooms were built for bankers and priced for them. Papermark is a secure data room for modern dealmakers, and it is more customizable and more branded than any other VDR on the market.
Security first. SOC 2 Type II, granular file-level permissions, dynamic watermarking on every page, and NDA agreements that sit on the link itself.
Open source and self-hostable. The codebase is public, and Enterprise can run it in your own environment, which matters when a buyer's IT team asks where the documents actually live.
Branded and white-labelled. Custom domain and full white-labelling, so the room carries your firm's name rather than a vendor's.
AI and MCP. 57 typed MCP tools over the Model Context Protocol let Claude, Cursor, ChatGPT or your own code drive the room, plus a REST API for everything else.
Chat with your data room. Papermark AI answers questions across the room and the documents in it, so you are not scrolling a folder tree to find one clause.
Built for technology deals. Permissions are set per file, so source code escrow and cohort retention can stay locked while the general file stays open.
Did not find the right technology M&A adviser?
If your company is smaller than these firms take, or you want a valuation view before signing an exclusive, the alternative is approaching strategic and sponsor buyers directly with technology counsel supporting you.
If none of the twelve above fits, the M&A advisors database lists every firm we have researched by city and by industry, with deal sizes and sectors side by side. Filter to Technology to compare these against each other, or check another market if you would rather work with a specialist elsewhere.